
─── SPECIALIST MICRO-ENTITY ACCOUNTANTS IN LONDON
FRS 105 Micro Entity Accounts in Ampthill
- Simple Fixed Pricing
- Fast Turnaround
- HMRC Compliant
- FRS 105 specialists
FRS 105 Micro-Entity Accounts
- FRS 105 accounts preparation
- Accounting records review
- Micro-entity eligibility review
- Companies House filing where applicable
- Corporation Tax support where included
- Director review
- FRS 105 accounting support
Find Your Company
Search for your company to continue with the accounting services
Start typing to search for companies...
Results
Years filing UK company accounts
Micro entity accounts submitted
Verified Google reviews
Typical Filing Turnaround
Trusted by Micro-Entity Businesses Across the UK
From newly incorporated companies to established owner-managed businesses, our clients trust us to prepare their accounts accurately and handle their annual filing requirements.
EXCELLENT Based on 302 reviews
 Posted on Google

 Ayotunde RufaiBest accountants we've ever had. Umer is ace, and makes everything easy and transparent.Posted on Google
 SofiaI had a really positive experience with Muhammad. He was incredibly quick to action everything and made the whole process straightforward and stress-free. He took care of everything promptly and kept me informed throughout, which was greatly appreciated. Muhammad was professional, responsive and genuinely helpful from start to finish. It was clear that he cared about providing a great service and making sure everything was handled properly. I would definitely recommend him to anyone looking for someone reliable, efficient and professional.Posted on Google
 Zest For Life
Trustindex verifies that the original source of the review is Google.
I worked with Accotx on a HMRC reclaim and overall, they did ultimately deliver on their promise, which I appreciate. The process did take longer than any of us expected, partly due to external delays with the tax authorities, and partly because there were some hiccups in communication and follow-up. However, despite those challenges, they stayed professional and stuck to the original agreed terms. If you’re considering using them, be prepared to stay in regular contact to keep things moving along. They are absolutely capable, have the expertise and willing to work with you, and overall improving their services over time. I would certainly return for any future needs.Posted on Google Pete WristSterling work. Many thanks to Muhammad and the team for all their help and expertisePosted on Google
 Hansen Personal TrainingWe have been a client for years - very quick responsive and personalised servicePosted on Google
 Jamie FletcherIt was a pleasure working with Anum on our accounts. The whole process was swift and effortless, and it was one less thing to worry about. I'd highly recommend them.Posted on Google
 Mansur LimanAccotax have been our accountants for many years now. We maintained them, because of their professionalism. In the last coiple of years, i have working with Imran, who has been very professional and helpful in guiding us through the whole process explaining and clarifying every aspect of it. Very prompt in responding to questions and patient with us even when we seem to be slow. I really enjoy working with him. Thank youPosted on Google
 Muna MohamoudI highly recommend Imran to anyone looking for a reliable and knowledgeable accountant. He helped me sort out a very complicated backlog of accounts and prepared my overdue tax returns with professionalism and attention to detail. Throughout the process, he was incredibly patient, took the time to answer all of my questions, and explained everything clearly. He guided me through each step and helped rectify issues that had built up over time, making what felt like an overwhelming situation much more manageable. I'm very pleased with the service I've received and truly appreciate his support. If you need help with your accounts or taxes, I would highly recommend Imran.Posted on Google
 Sergey MI had a positive experience with Accotax. The work was completed promptly, my tax return was successfully filed, and I received a refund of overpaid tax. I found the cooperation efficient and helpful. Special thanks to Muhammad Saifullah for his assistance.Posted on Google
 Ebba QureshiFabulous team at ACCOTAX - very efficient and good response time . Honest and professional with their work. I would highly recommend them even if you’re a young start up - or a large business they have it covered .
─── FRS 105 EXPLAINED
FRS 105 Explained: The Micro-Entities Regime in Plain English
Who Can Use FRS 105 in the UK? A Guide for Ampthill Micro-Entities
A company generally needs to meet at least 2 of these 3 conditions.
Business Turnover
Annual Turnover of £1 Million or less. (£632,000 previously)
Balance Sheet
Balance sheet total of £500,000 or less.(£316,000 previously)
Company Size
On an average 10 or less employees (10 or less previously)
─── What We Review
Everything Your Micro-Entity Company Is Required to Get Right
Most compliance problems are not deliberate. They come from a missed deadline, an accounts template that no longer matches FRS 105, or dividends taken without the paperwork to support them. Our review covers each area in turn and reports back in plain English.
FRS 105 Balance Sheet
A statutory balance sheet prepared to the FRS 105 format, using the reduced disclosure the micro-entities regime allows.
Profit & Loss Account
A profit and loss account prepared for your own records and for your Corporation Tax computation, without public filing.
Required Notes & Disclosures
Preparation of the notes and disclosures required for the company's accounts under the applicable reporting requirements.
Corporation Tax Support
Separate Corporation Tax support can be provided where included in the agreed service. The Corporation Tax calculation is governed by tax rules rather than FRS 105.
Companies House Filing
Your FRS 105 accounts filed with Companies House in the correct format, before your accounts filing deadline.
Director Copy Pack
A full signed copy of your accounts and tax return, ready for your bank, mortgage lender or accountant records.
─── How It Works
How Our FRS 105 Preparation Process Works
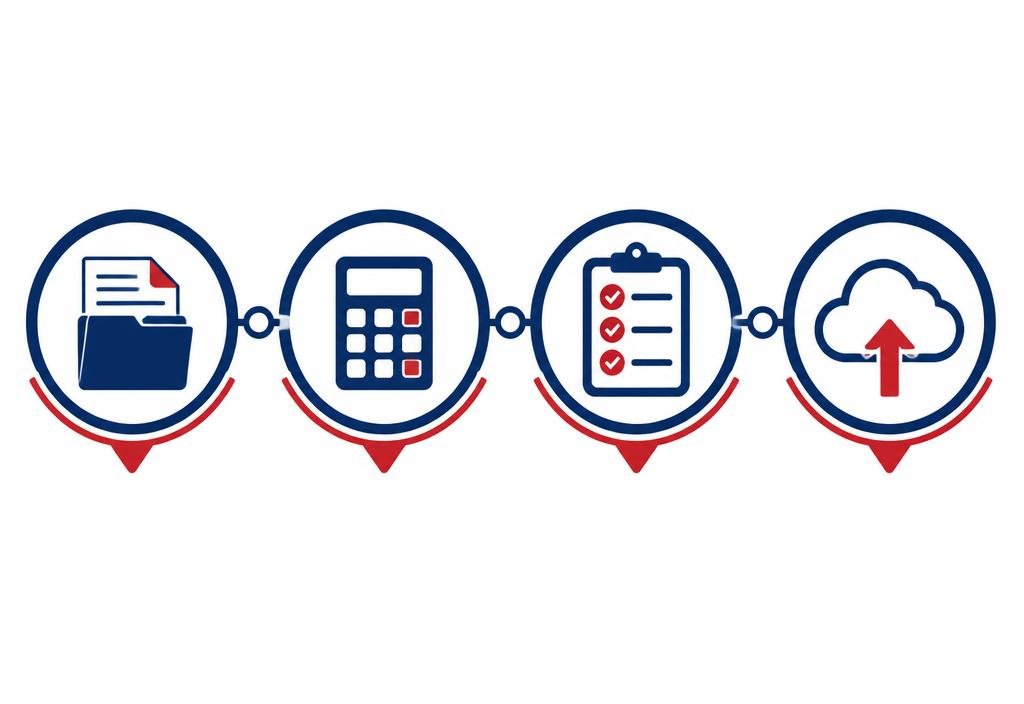
Share Your Records
Send your bank statements, sales and purchase records, expenses and payroll details through our secure digital platform.
We Prepare Your FRS 105 Accounts
Our accountants confirm you qualify for the micro-entities regime, then prepare your accounts and CT600 from your records.
Review & Approve
We send draft accounts with clear explanations of the figures, and adjust anything before anything is submitted.
We File Where Required
Once approved, we can assist with the relevant Companies House filing and any separately agreed tax submission.
─── WHY CHOOSE US
Why Choose Our FRS 105 Accountants?
We keep micro-entity accounts straightforward, transparent and easy to manage for busy company directors.
FRS 105 Accounts Support
The micro-entities regime is all we do, so your accounts are prepared to the right standard first time.
Paperless Onboarding
Get set up in minutes with a fully digital, secure process — no printing, posting or office visits.
Deadline Management
We track your Companies House and HMRC deadlines and prompt you early so late filing penalties are avoided.
Clear, Transparent Pricing
One transparent fixed fee covers preparation, the tax return and both filings. No hourly billing.
─── WHO WE HELP
FRS 105 Support for Micro-Entities Across the UK
One-Director Companies
Straightforward FRS 105 accounts and Corporation Tax filing for owner-managed limited companies.
Freelancers & Contractors
Accounts and compliance support for contractors trading through a qualifying limited company.
Startups & Small Companies
Practical support for newly incorporated companies filing their first set of micro-entity accounts.
Dormant & Low-Activity Companies
Dormant company accounts and FRS 105 accounts for LLPs that meet the micro-entity thresholds.
FRS 105 Micro Entity Accounts: Professionally Prepared, Accurately Reported
Need Help With FRS 105 Micro Entity Accounts in Ampthill?
─── FAQs
FRS 105 Accounts Preparation FAQs
Still unsure where you stand? Reach out to our UK team at info@microentityaccounts.co.uk and we will review your filing history with you.
FRS 105 is the UK financial reporting standard that applies when a qualifying company chooses to use the micro-entities regime. It provides a simplified basis for preparing financial statements, with lighter measurement requirements and far fewer disclosures than a fuller framework such as FRS 102. In practice, accounts prepared under FRS 105 typically include a balance sheet, a profit and loss account and a small number of notes, and in many cases a more abbreviated version can be filed. FRS 105 is purely about accounting and reporting. It does not determine how much Corporation Tax is payable, and it does not replace a CT600.
FRS 105 is intended for companies that qualify as micro-entities under the UK regime and that choose to apply it. Qualifying means meeting the applicable size conditions and not falling within any of the exclusions that can rule a company out regardless of its size. It is worth stressing that qualifying does not oblige a company to use FRS 105 — a qualifying company may instead apply FRS 102 or another framework where that is more appropriate for its reporting needs, its lenders or its group. Directors should consider the choice deliberately rather than assuming the simplest option is automatically the right one.
No. The micro-entities regime is an available accounting regime, not a mandatory one. A company that meets the size conditions can choose to apply FRS 105, but it is equally entitled to prepare its accounts under FRS 102 — including the small entities provisions — or another framework that applies to it. The decision usually comes down to what the accounts need to do: whether they are mainly for Companies House and HMRC, or whether a bank, investor, buyer or parent company expects a fuller level of disclosure. Because the choice affects what the accounts look like, it is best considered before the year-end work begins.
For accounting periods beginning on or after 6 April 2025, a company generally needs to meet at least 2 of the following 3 conditions: turnover of no more than £1 million, a balance sheet total of no more than £500,000, and an average of no more than 10 employees. These are the applicable size conditions, and how each is measured follows the rules of the regime rather than a simple reading of the year's figures. Meeting 2 of the 3 does not settle the question on its own, because other eligibility rules and exclusions can also apply — certain entity types are outside the regime whatever their size. It is always worth checking the specific position rather than assuming.
Both are UK financial reporting standards, but they sit at different levels of complexity. FRS 105 is the micro-entities standard: it is deliberately pared back, with simplified measurement and a much shorter list of disclosures, and it is only available to companies using the micro-entities regime. FRS 102 is the fuller standard, and it includes small entities provisions that many small companies use; it generally requires more detailed recognition, measurement and disclosure. The practical effect is that FRS 105 accounts tend to be shorter and quicker to assemble, while FRS 102 accounts give readers more information. Which one is right depends on your company, not on which is simpler.
Where a company is required to file annual accounts, the accounts prepared under FRS 105 are its statutory accounts, and they would normally be delivered to Companies House. The micro-entities regime does allow a more abbreviated form of filing in many cases, so what is filed may look shorter than the full set of financial statements prepared for the directors. Filing obligations and deadlines depend on the company's own circumstances, including whether it is trading, dormant or newly incorporated. Filing the accounts is a separate step from dealing with Corporation Tax, and completing one does not automatically complete the other.
Yes, they are two different things. FRS 105 governs how the financial statements are prepared and what they contain. A CT600 is the Corporation Tax Return submitted to HMRC, and it is calculated using tax rules rather than accounting rules. That means figures in the accounts are usually the starting point for a tax computation, but adjustments — such as add-backs for disallowable expenses or claims for capital allowances — can change the taxable profit. The two also have their own submission arrangements and dates, so it helps to plan them together rather than treating one as finished when the other is still outstanding.
It can, if it qualifies for the micro-entities regime and chooses to apply it. Newly incorporated companies are not excluded simply because they are new, and a first set of accounts from a small, straightforward trading company will often fit comfortably within the size conditions. However, first-period accounts can create complications: the period may run for longer than twelve months, and the way the size conditions are assessed in that situation is not always obvious. If your company has just started trading in the Ampthill area, it is worth reviewing the figures and the reporting options before the first accounts are due.